
In this article 12 sections
Your legal floor depends on what you haul. Federal rules in 49 CFR 387.9 require $750,000 of public liability for for-hire, non-hazardous freight in trucks of 10,001 lbs GVWR or more, $1,000,000 for oil and most hazardous materials, and $5,000,000 for bulk hazardous substances and certain explosive, poison-gas and radioactive loads. Many brokers and shippers ask for $1,000,000 regardless.
On price, Progressive Commercial’s 2025 data puts the average new for-hire policy at $926 a month for transport truckers and $734 for specialty truckers (clean record, liability plus physical damage), and ATRI reports insurance premiums were still rising in early 2026.
Compliance is not just the policy: your insurer must file the MCS-90 endorsement and a BMC-91 or BMC-91X certificate in your exact legal name, and you need a BOC-3 process-agent filing before you can operate under your own authority.
Figures cross-checked against the eCFR (49 CFR Part 387), FMCSA and published insurer and ATRI data. See our sourcing policy.
Commercial truck insurance is the coverage a motor carrier must have in effect before a truck can haul freight, and federal rules set the minimum. This guide puts three things in one place: the FMCSA minimum liability limits by cargo type, the filings your insurer must make, and the factors that set your premium, with each figure tied to its regulation or published source.
Quick answer: Under 49 CFR 387.9, interstate trucks of 10,001 lbs GVWR or more need at least $750,000 of liability for non-hazardous for-hire freight, $1,000,000 for oil and most hazardous materials, and $5,000,000 for bulk hazardous substances. For-hire fleets of only lighter vehicles hauling non-hazardous freight need $300,000 (49 CFR 387.303T). Proof is the MCS-90 endorsement plus a BMC-91 or BMC-91X filing.
Missing a specific coverage, such as bobtail or cargo insurance, can leave a gap that the federal minimum does not fill. The minimums protect the public; they do not pay to repair your truck or replace a customer’s load.

This guide is written for owner-operators managing their own vehicles, small-fleet owners overseeing multiple trucks, and anyone setting up new operating authority. Our editorial team built it from the Code of Federal Regulations and from published premium benchmarks from insurers and ATRI.
For how insurers rate risk on personal vehicles, which shares several factors with truck pricing, see what affects car insurance rates.
📌 2026 Commercial Truck Insurance: Quick Intelligence Summary
Key Facts at a Glance
| Avg. Monthly Cost | $734 (for-hire specialty) to $926 (for-hire transport), Progressive Commercial 2025 new policies |
| Approx. Annual Cost | About $8,800 to $11,100 per power unit (our arithmetic on the monthly averages) |
| Required Liability | $750,000 non-hazardous (10,001+ lbs) | $1,000,000 oil and most hazmat | $5,000,000 bulk hazmat (49 CFR 387.9) |
| Light Vehicles | $300,000 for for-hire fleets of only vehicles under 10,001 lbs, non-hazardous (49 CFR 387.303T) |
| Proof of Coverage | MCS-90 endorsement or MCS-82 surety bond (49 CFR 387.7) |
| FMCSA Filings | BMC-91 or BMC-91X certificate; BOC-3 process agents |
| Cancellation Notice | 35 days in writing (49 CFR 387.7) |
| Insurance Cost Trend | Premiums up 6.4% in Q1 2026 (ATRI) |
Federal Minimum Liability Limits by Cargo Type
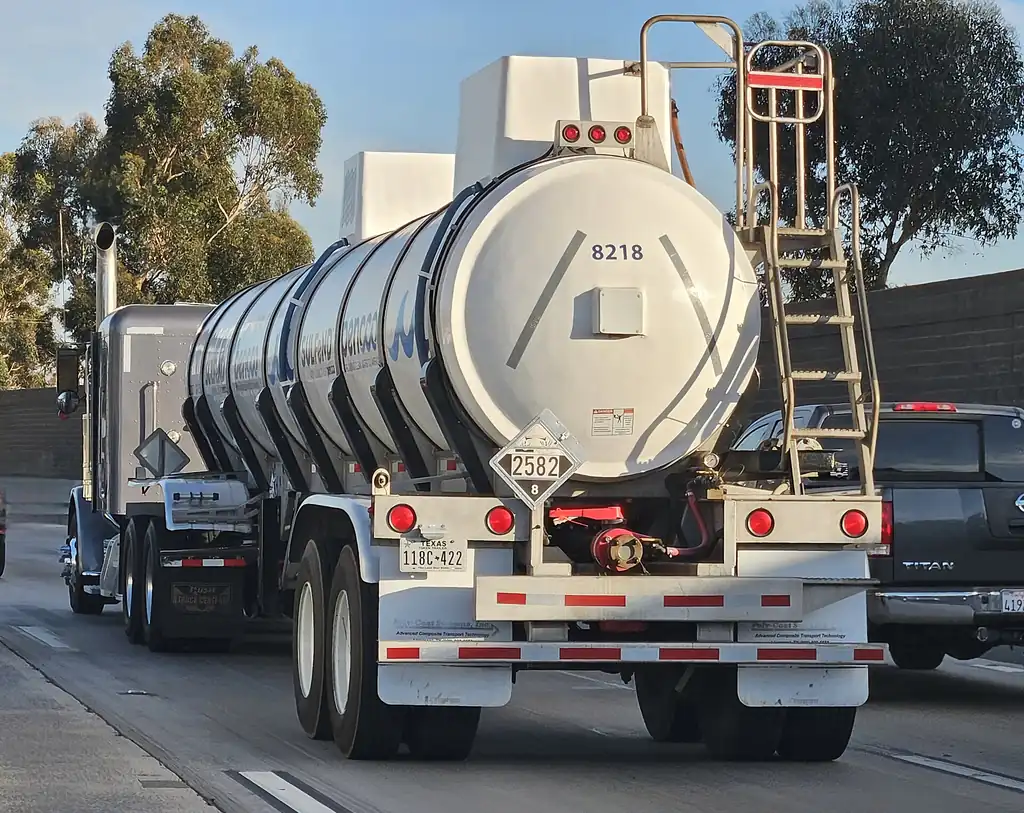
The $750,000 figure most people quote is only one row of the federal schedule. The limit that applies to you depends on what you haul, whether you are for-hire or private, and the weight rating of your truck. These are the public liability minimums in 49 CFR 387.9 (also on Cornell LII), plus the light-vehicle row in 387.303T.
| What you haul | Who it applies to | Truck weight (GVWR) | Minimum liability |
|---|---|---|---|
| Non-hazardous property | For-hire, interstate or foreign | 10,001 lbs or more | $750,000 |
| Oil; hazardous waste, hazardous materials or substances not in the $5 million rows | For-hire and private; interstate in any quantity, intrastate in bulk only | 10,001 lbs or more | $1,000,000 |
| Hazardous substances in bulk (cargo tanks, portable tanks, hopper-type vehicles); bulk Division 1.1-1.3 explosives; bulk Division 2.1 or 2.2 gases; bulk Division 2.3 Hazard Zone A gases; bulk Division 6.1 Packing Group I, Hazard Zone A; highway route controlled quantities of Class 7 | For-hire and private; interstate, foreign or intrastate | 10,001 lbs or more | $5,000,000 |
| Bulk Division 1.1-1.3, Division 2.3 Hazard Zone A, Division 6.1 Packing Group I Hazard Zone A or highway route controlled Class 7 materials | For-hire and private, interstate or foreign | Under 10,001 lbs | $5,000,000 |
| Non-hazardous property, fleet of only light vehicles | For-hire (49 CFR 387.303T(b)(1)(i)) | Under 10,001 lbs | $300,000 |
“In bulk” generally means containment systems holding more than 3,500 water gallons, but for Division 1.1-1.3 explosives and the Hazard Zone A poison materials, any quantity counts as bulk (49 CFR 387.5). For-hire carriers of household goods fall under a separate cargo rule: the security amounts in 49 CFR 387.303T are $5,000 per vehicle and $10,000 per occurrence. Under 49 CFR 387.7, a motor carrier may not operate a vehicle until the required financial responsibility is in effect. The rules are minimums. Brokers, shippers and lenders often ask for more, which is why $1,000,000 shows up in so many contracts. This is general information, not legal or insurance advice.
Compliance & Authority Section
The Federal Motor Carrier Safety Administration (FMCSA) enforces these limits. Under 49 CFR 387.17, a knowing violation carries a civil penalty, and a continuing violation counts as a separate offense each day. Without the required filings, FMCSA will not grant or keep your operating authority.
The 2026 Compliance Checklist:
- Liability limits: at least the 387.9 amount for your cargo, or the higher limit your broker or shipper requires.
- MCS-90 endorsement (or MCS-82 surety bond): the proof of coverage required by 387.7, kept at your principal place of business and shown to the public on reasonable request.
- BMC-91 or BMC-91X: the certificate your insurer files with FMCSA for for-hire authority.
- BOC-3 filing: process agents for each state you are authorized to operate in and each state you travel through.
- Continuous coverage: cancellation requires 35 days’ written notice, so a lapse can end your authority.
Filings Your Insurer Makes: MCS-90, BMC-91/BMC-91X and BOC-3
A policy alone does not make you compliant. Paperwork must also reach the regulator, and mistakes here are a common reason authority is delayed or a policy is rejected.
- MCS-90 endorsement: 49 CFR 387.15 says the endorsement must be on the form the FMCSA prescribes, that coverage stays in effect continuously until terminated as required by 387.7, and that the endorsement and any surety bond must be issued in the exact name of the motor carrier. Make sure the name on your policy matches your USDOT registration.
- BMC-91 vs. BMC-91X: for-hire carriers need certificates of insurance, surety bonds or other security filed with and accepted by FMCSA in the amounts set by 387.303T. Under 49 CFR 387.313T, a BMC-91 is filed for the full security limit, while a BMC-91X can show full coverage or any level of aggregation. If a primary and an excess insurer together make up your limit, each one files its own BMC-91X. Household goods carriers also file cargo coverage on Form BMC-34, or a BMC-83 surety bond.
- BOC-3 process agent: the section of the rule currently in effect, 49 CFR 366.4T, requires a designation for each state in which you are authorized to operate and each state traversed. Under 366.5T, the blanket-designation rule in effect, many carriers use a blanket agent that has filed a list of process agents for each state. (The original 366.4 text, which names all 48 contiguous states and DC, is suspended; see also 49 CFR 366.4.)
- Timing for new authority: 49 CFR 365.109T lists the BMC-91 or 91X and the BOC-3 among filings due after your application notice is published in the FMCSA Register. Follow the deadline FMCSA gives you, because authority is not granted until both are on file.
Ask the agent for copies of every filing and keep them with your registration records. If you change legal name or add a business entity, reissue the endorsement in the new exact name.
What Drives Your Premium
Insurers price commercial truck coverage from a set of risk factors. Progressive Commercial lists these as the main ones:
- USDOT authority: leasing onto a motor carrier is usually cheaper than running under your own authority, because the carrier typically covers primary liability while you are under dispatch.
- Coverage requirements: the more coverage and the higher the limits your cargo or contracts require, the higher the premium.
- Cargo: value, theft potential and hazard level; hazardous or high-value loads cost more to insure than produce.
- Operating radius: crossing state lines and long regional routes cost more than local work.
- Truck type and age: heavy semis cost more than lighter trucks, and newer trucks with safety features may cost less.
- Driving history: violations weigh more heavily than on personal auto policies.
- Location: rates vary by state and with traffic and accident levels.
Some insurers also offer discounts for sharing data from your electronic logging device (ELD). Progressive, for example, says new customers who enrolled in its Smart Haul ELD program between February and August 2025 saved an average of $1,261. The same sensor-and-data trend shows up in passenger cars; see the Best Self Driving Cars of 2025.
Real-World Scenario: The Cost of Gaps
Consider a typical scenario: a leased owner-operator skips bobtail truck insurance, thinking he is safe without a trailer. He hits a car on his way home. Because he wasn’t “under dispatch,” the motor carrier’s policy may not respond, leaving him personally exposed.
This is why the question of which policy applies, and when, matters as much as the limit. Never assume that the carrier’s liability automatically follows you when you’re off dispatch; get the answer in writing.
How to Get the Best Quote: Step-by-Step

Step 1: Preparation
Gather your motor vehicle report (MVR) for the last three years, your USDOT number, the VINs of every truck and trailer, your cargo types and your operating radius.
Step 2: Execution
Request quotes from at least three commercial truck insurers for the same limits, coverages and deductibles, stating your exact operation, such as a single truck under your own authority or a truck leased onto a carrier.
Step 3: Verification
Check each insurer’s AM Best financial strength rating and confirm the insurer will file the required MCS-90 endorsement and BMC-91 or BMC-91X certificate with FMCSA in your exact legal name.
Coverage Checklist and 2026 Cost Signals
Progressive Commercial lists these coverages for truck policies: primary liability, non-trucking (bobtail) coverage, physical damage, trailer interchange, motor truck cargo and combined single limit (CSL) liability. Use the list when you ask for quotes so each insurer prices the same package.
- Primary liability at or above your broker or shipper’s limit, not just the federal minimum.
- Physical damage with a deductible you can cover without borrowing.
- Motor truck cargo with a limit that matches the most valuable load you haul.
- Bobtail or non-trucking liability if you are leased to a carrier, and a written answer on when the carrier’s policy applies.
- Trailer interchange if you pull trailers owned by others.
- A quote with and without telematics, so you can see what an ELD-data discount is worth.
On cost, Progressive’s 2025 new-policy data (liability and physical damage, no driver violations) lists an average of $926 a month per power unit for for-hire transport truckers and $734 for specialty truckers. Progressive also cites an average $1,261 savings for new Smart Haul customers who share ELD data (February to August 2025 enrollments). The American Transportation Research Institute (ATRI) reported a record 2025 operating cost of $2.336 per mile, and first-quarter 2026 data showing insurance premiums up 6.4%.
Coverage Types at a Glance
| Coverage | What it pays for | Who usually needs it |
|---|---|---|
| Primary liability | Injuries and property damage you cause to others | Every carrier; the federally required coverage |
| Non-trucking (bobtail) liability | Liability gaps when a leased truck is not under dispatch | Owner-operators leased onto a carrier |
| Physical damage | Repair or replacement of your own truck | Usually required when the truck is financed or leased |
| Motor truck cargo | Lost or damaged freight | Carriers whose contracts require it |
| Trailer interchange | Damage to trailers you pull but do not own | Carriers under trailer interchange agreements |

Final Verdict
Start with the legal floor for your cargo in 49 CFR 387.9, then raise the limit to whatever your brokers and shippers require. Make sure your insurer files the MCS-90 and BMC-91 or BMC-91X in your exact legal name, file your BOC-3, and compare at least three quotes on identical coverage. Review limits whenever your cargo, radius or contracts change.
Frequently Asked Questions: Commercial Truck Insurance
How much does commercial truck insurance cost?
How much is commercial truck insurance per month?
Who has the cheapest commercial truck insurance?
What is commercial insurance?
What is the minimum liability insurance for a commercial truck?
Under 49 CFR 387.9, a for-hire interstate carrier of non-hazardous property in a truck of 10,001 lbs GVWR or more needs at least $750,000. Oil and certain hazardous materials need $1,000,000, and certain bulk hazardous substances need $5,000,000.
Do I need an MCS-90 endorsement?
Federal rules at 49 CFR 387.15 require the MCS-90 endorsement on the FMCSA-prescribed form. It stays in effect until terminated as required, and it must be issued in the exact name of the motor carrier.
What is a BOC-3 filing?
A BOC-3 designates process agents who can accept legal papers for you. Under 49 CFR 366.4T, the version currently in effect, a motor carrier must designate an agent for each state it is authorized to operate in and each state it travels through; many carriers use a blanket agent service under 366.5T.
What insurance does a for-hire truck under 10,001 lbs need?
Under 49 CFR 387.303T(b)(1)(i), a for-hire carrier of non-hazardous property whose fleet includes only vehicles under 10,001 lbs GVWR needs $300,000. Certain explosives, poison-inhalation and radioactive loads still need $5,000,000 regardless of weight.
What is the difference between BMC-91 and BMC-91X?
Under 49 CFR 387.313T, a BMC-91 certificate is filed for the full required limit, while a BMC-91X can show full coverage or any level of aggregation, for example when primary and excess insurers together reach the limit. Each insurer in an aggregation files its own BMC-91X.
How much notice is needed to cancel truck liability insurance?
49 CFR 387.7 requires 35 days’ written notice from either the insurer or the motor carrier, counted from the date the notice is transmitted. Coverage must otherwise stay in effect continuously until terminated.
⚠️ Professional Notice:
This guide is provided for educational purposes. NextCarReview is not liable for any financial losses or insurance claim denials resulting from actions taken based on this content. Insurance laws and FMCSA regulations vary by state and operation type. Always consult with a licensed insurance broker and review your specific policy documents before making coverage decisions.
For official rules, ratings and consumer guidance on this topic, see:
Related reading: 5 Tips for Getting the Cheapest Auto Insurance Quotes In 2026, Ultimate Guide: How to Find the Best Quotes for Car Insurance.
Sources
- 49 CFR 387.9: financial responsibility minimum levels
- eCFR: 49 CFR Part 387, minimum levels of financial responsibility
- Progressive Commercial: commercial truck insurance cost
- ATRI operational costs of trucking, 2026 update (via Trucking Info)
- 49 CFR 387.303T: minimum security amounts
- 49 CFR 387.313T: forms and procedures (BMC-91, BMC-91X)
- 49 CFR 387.15: MCS-90 endorsement
- 49 CFR 387.7: financial responsibility required
- 49 CFR 366.4: process agent designation (BOC-3)
- eCFR: 49 CFR Part 366, including 366.4T and 366.5T
- eCFR: 49 CFR Part 365, including 365.109T
Morgan Reyes is the founder and editor-in-chief of NextCarReview, which Morgan launched in August 2024. A 2022 graduate of Columbia University, Morgan is based in New York and writes and edits the site’s reviews, comparisons and buying guides. Morgan does not road-test vehicles. Every article is built from published primary data: EPA FuelEconomy.gov ratings, NHTSA crash ratings, recalls and owner complaints, IIHS results, and manufacturer specifications and pricing, with each figure cited and checked before publication. Contact: admin@nextcarreview.com